


I got a text this week from an author I will not name. He says coking coal is finished, because China has found a way to replace steel.
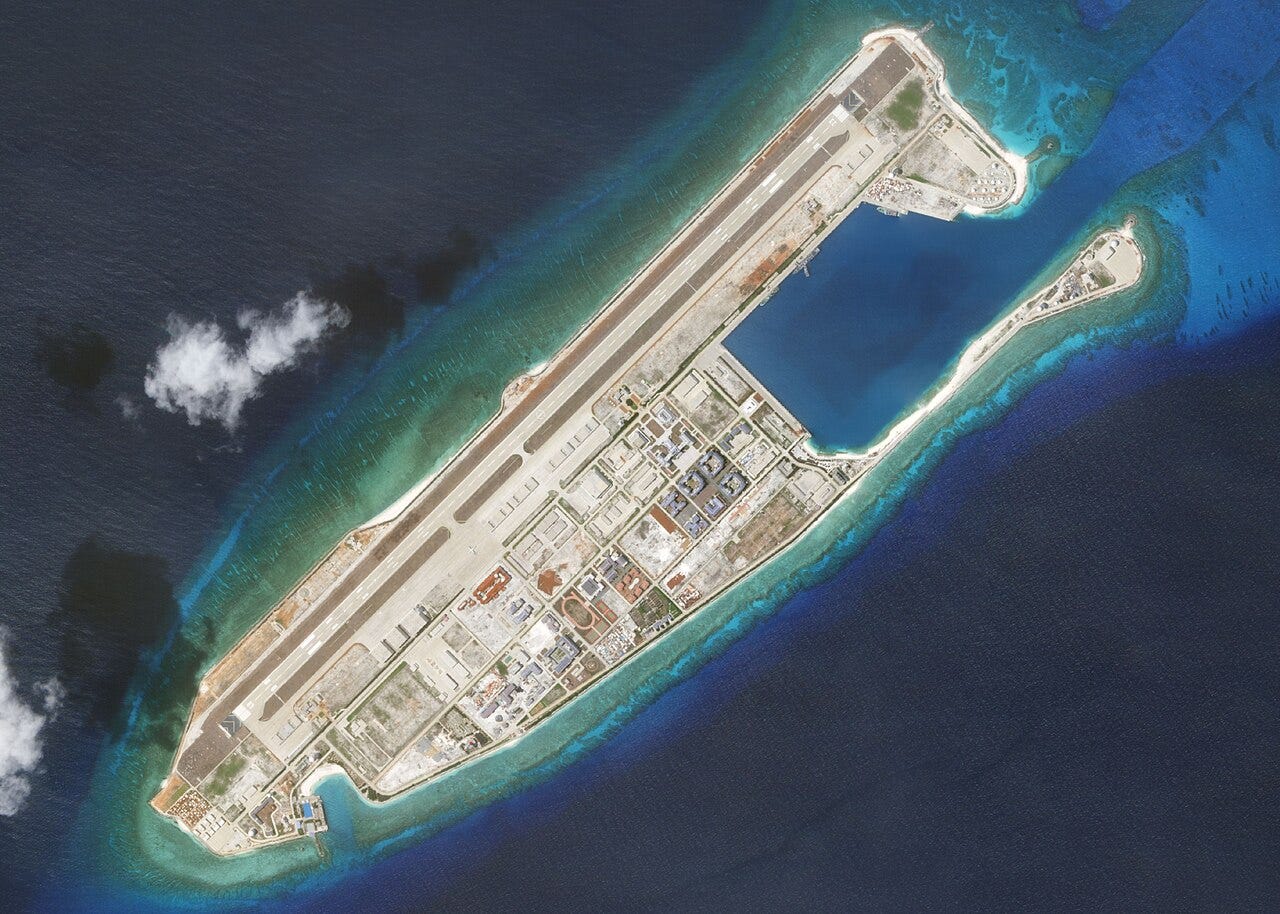
His argument goes like this. Take basalt, the black volcanic rock that paves half the planet. Melt it. Push the molten rock through nozzles made of platinum and pull it into threads finer than hair. Weave the threads into rebar, car frames, turbine blades. The result is eight times stronger than steel at a quarter of the weight. It does not rust, it does not conduct, and radar cannot see it. China already pours it into the artificial islands in the South China Sea, where steel rebar corrodes in 25 years and basalt lasts 100. No steel, no blast furnace. No blast furnace, no coke. No coke, no Warrior, no Alpha, no post.
I say coking coal is not going anywhere.
Basalt melts at about 1,400 degrees. Something has to make that heat, and in China it is coal. The world makes 1.9 billion tons of steel a year. It makes a few tens of thousands of tons of basalt fibre, enough for a few islands and some wind blades. And basalt has one property he left out. Steel bends. A beam sags, a bridge groans, people get out. Basalt fibre holds until the second it shatters, with no warning at all. Nobody builds a bridge, a tower or a ship out of a material that cannot bend. Two thirds of the world’s steel still comes out of a blast furnace, and India is building more of them.
What is going out is the margin of the company that digs the most coking coal in America.
Alpha Metallurgical digs about the same tonnage as Warrior, a good part of it the same High Vol A, and it has lost money three quarters in a row. $11 million, $12 million, and this morning $9.3 million more. Warrior made $36 a ton on its mix. Alpha cleared $14 at the mine, and the rest of the company ate it.
Alpha used to be the biggest cannibal in coal. Since 2022 it bought back 7.1 million of its own shares for $1.2 billion, more than a third of the company, at an average price of $166. When the company slowed down, its directors did not. Michael Gorzynski took 10,000 shares on August 21 at $209. Kenneth Courtis, who owns 8% of Alpha, kept going. On August 20 he bought at $193. The next day at $210. On August 28 he paid $229. On September 8 he bought again. Fifty thousand shares in three weeks, about $10 million of his own money. Then the quarter ended and the window closed.
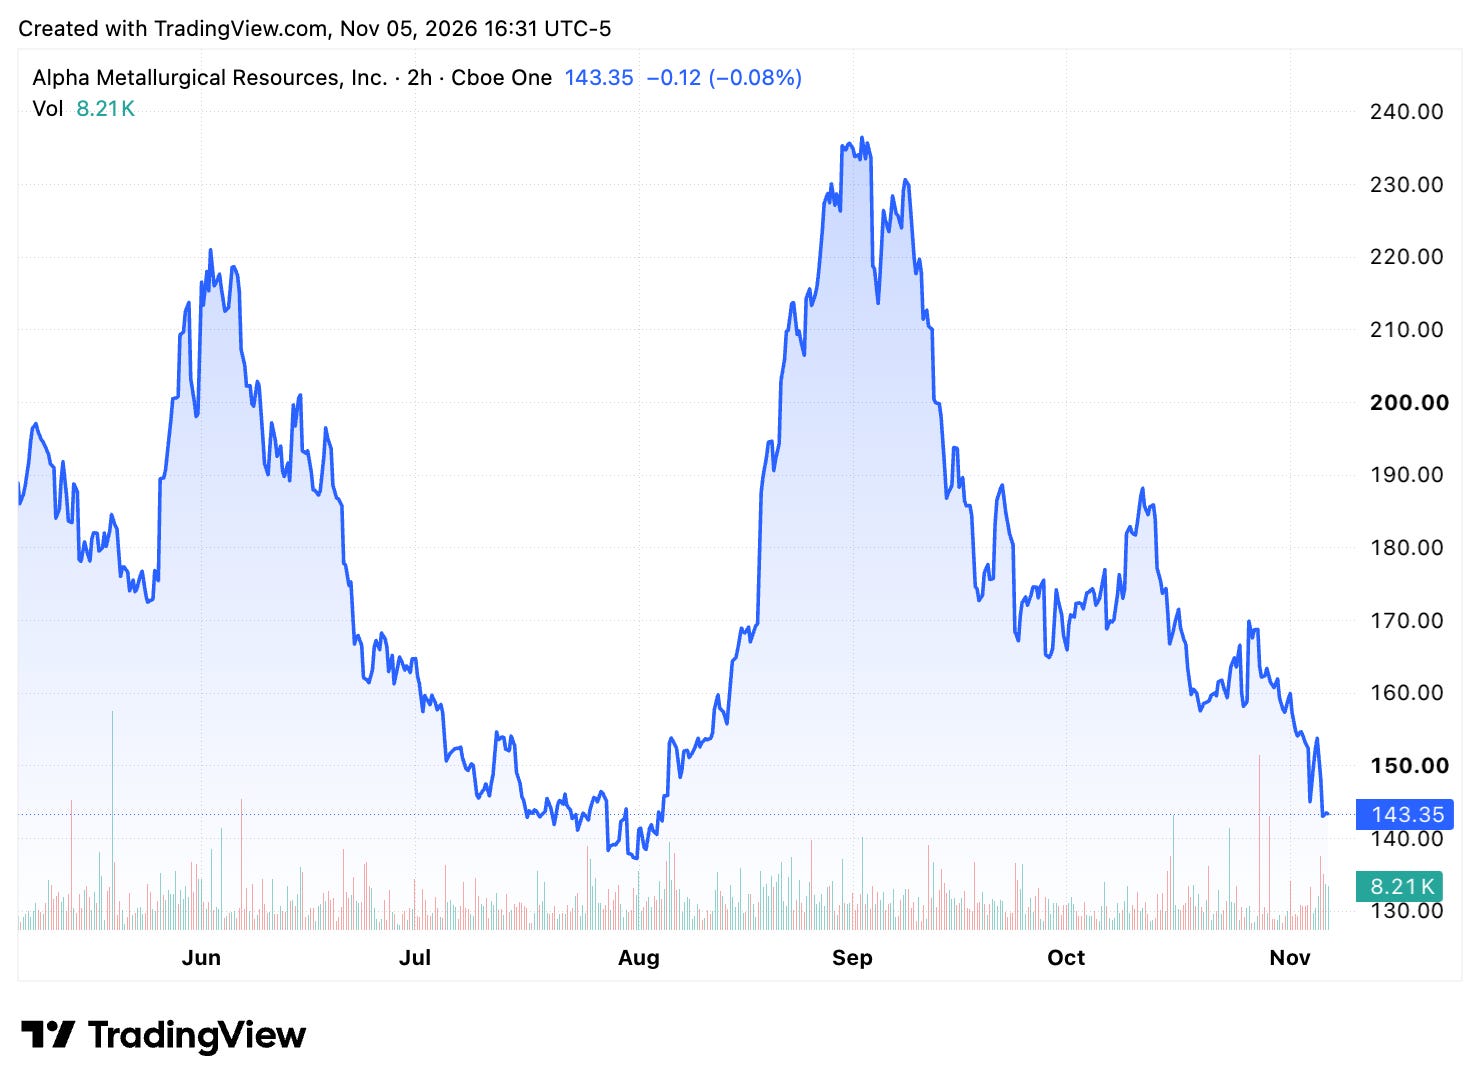
Courtis’s stake was worth $234 million the day he last bought. Today it is worth about $155 million. Close to $80 million gone in eight weeks, and he was not allowed to buy a single share on the way down. Next week the window opens again.
Either the man who owns 8% of this company is wrong, or he saw something in Alpha’s own numbers that the market did not. I went through this morning’s report line by line and I found it. It is one line, and it is ten cents wide. It says why Alpha’s losses are not the problem but the floor, why Warrior’s price cannot fall further, and why the next move in High Vol A coal starts in West Virginia and not in Alabama.
Below the line is that ten cents. The real short interest once you take out the shares Courtis and the index funds. Whether the company that paid $166 for a third of itself is buying in the $150s. And one sentence from Alpha’s CEO that every Warrior shareholder needs to hear.
And whether the man who paid $229 buys again next week.
