

What I am looking for in investing is just a handful of completely obvious opportunities, so wildly mispriced and undervalued that you barely even need to think about them. Something “strange.” Something that makes absolutely no sense.
So far, I have found a few such situations.
A company that wants to return all its cash to shareholders through buybacks, and in just a few years has already bought back more than $1.3 billion worth of shares. My assumption is that over its lifetime, it will generate $10 billion, $20 billion, or even $40 billion. Maybe even more. The price Mr. Market offered me? $2 billion for the whole thing. Okay, I’ll pay.
If almost every cent of those earnings goes into buybacks, and it will, the company could buy itself several times over. Of course, that is not possible because the stock price would have to rise first. But that is exactly what makes this situation “strange.”
The second company has some drilling rigs, and everyone knows that a new deepwater rig costs more than $1 billion and that the last one humanity will ever build has probably already been built. Nobody wants to build them anymore. They are expensive, they take a long time to build, and some companies have even gone bankrupt trying, so everyone gets a little “shiver” just hearing the subject mentioned. This company will soon have 73 rigs in total.
Mr. Market was asking $4 billion for it. I said, okay, I’ll pay. And when most of those rigs are working, or dare I say all of them, the economics of this business look truly wonderful. That is what makes this situation “strange.”
The third company is making an acquisition. It is paying $1.3 billion for some car dealerships. With those dealerships, the entire company will have 259 in total. Mr. Market offered me the whole company for $2.8 billion, all 259 dealerships. I said, sure, I’ll pay. And these guys have already bought back 54% of all the shares that once existed. Pretty “strange.”
And there is one more thing that makes all three companies very unusual. They plan to return all that cash to shareholders. And all three are owned by superinvestors who have also found something “strange” in them.
In today’s AI madness, something like this is truly rare to find…
Then, a few days ago, a reader pointed me to another “strange” situation.
There is an offshore company that runs six of the only sixteen rigs of their kind in the entire world. Nobody is building new ones. It bought three of those rigs for $85 million, and today those three alone bring in $138 million a year. It has almost no debt. It trades for less than four times EBITDA. And it pays its shareholders a 20% annual dividend.
Hated, unknown, ignored, alone. On its website it says it “has an ambition to distribute all excess cash to shareholders quarterly”. Man, so very few companies are willing to write it down.
Is that “strange” enough? For me, it is.
So let’s jump straight down the rabbit hole.
Why I got excited
The company is SED Energy Holdings. It trades in Oslo under the ticker ENH.
I started with what the company says about itself.
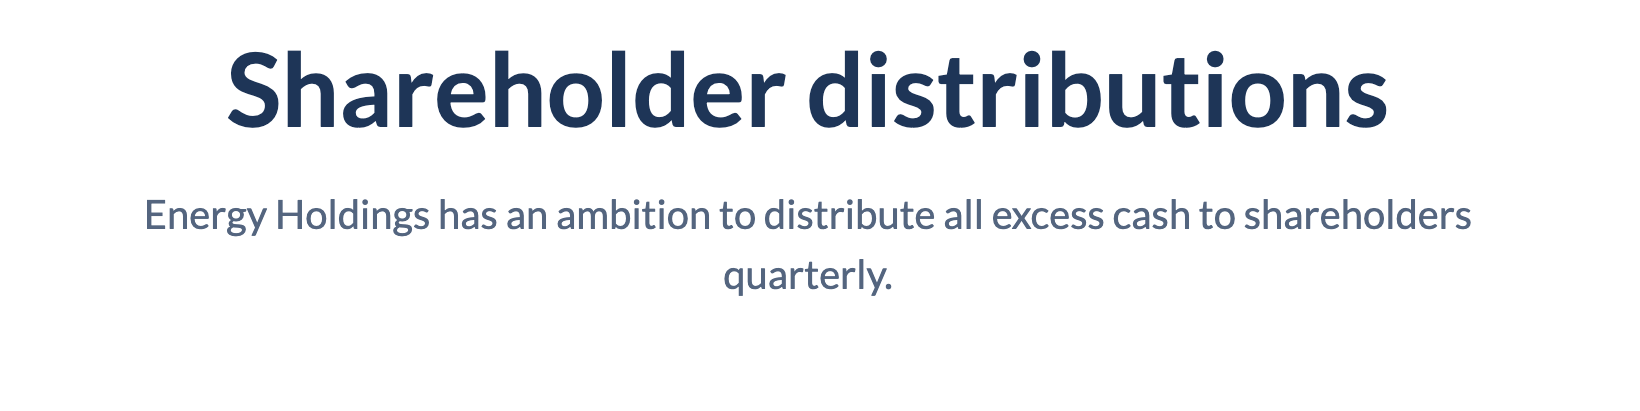
Man, I love that sentence!
And so far they have done what they said. Since May 2025 the company has paid or approved $132.5 million to shareholders, while the whole company is worth about $490 million. For this year management is guiding for $90 to $110 million. At today’s price that is 20%. So the 20% is not something a blogger made up. It comes straight from management.
Then I wanted to understand what they actually own. They own tender rigs.
A normal offshore rig carries everything it needs. A tender rig is basically half a rig. The drilling equipment gets lifted onto the oil company’s own platform, and next to it floats a barge with the crew, the pipes and the power. When the wells are done, everything moves to the next platform.
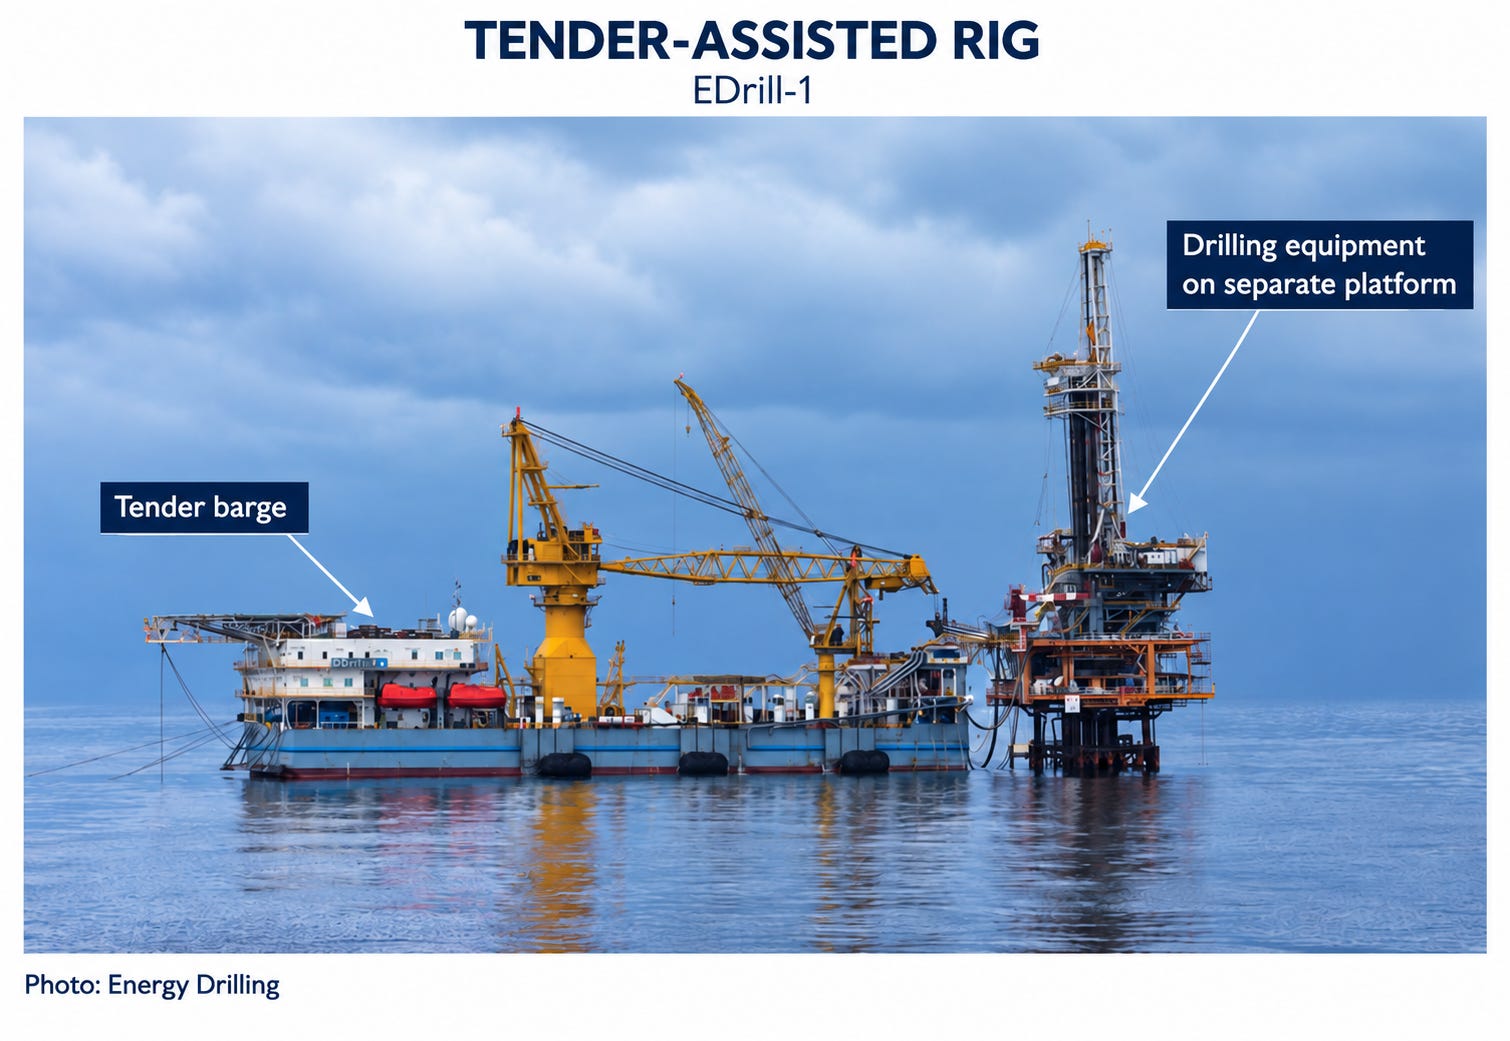
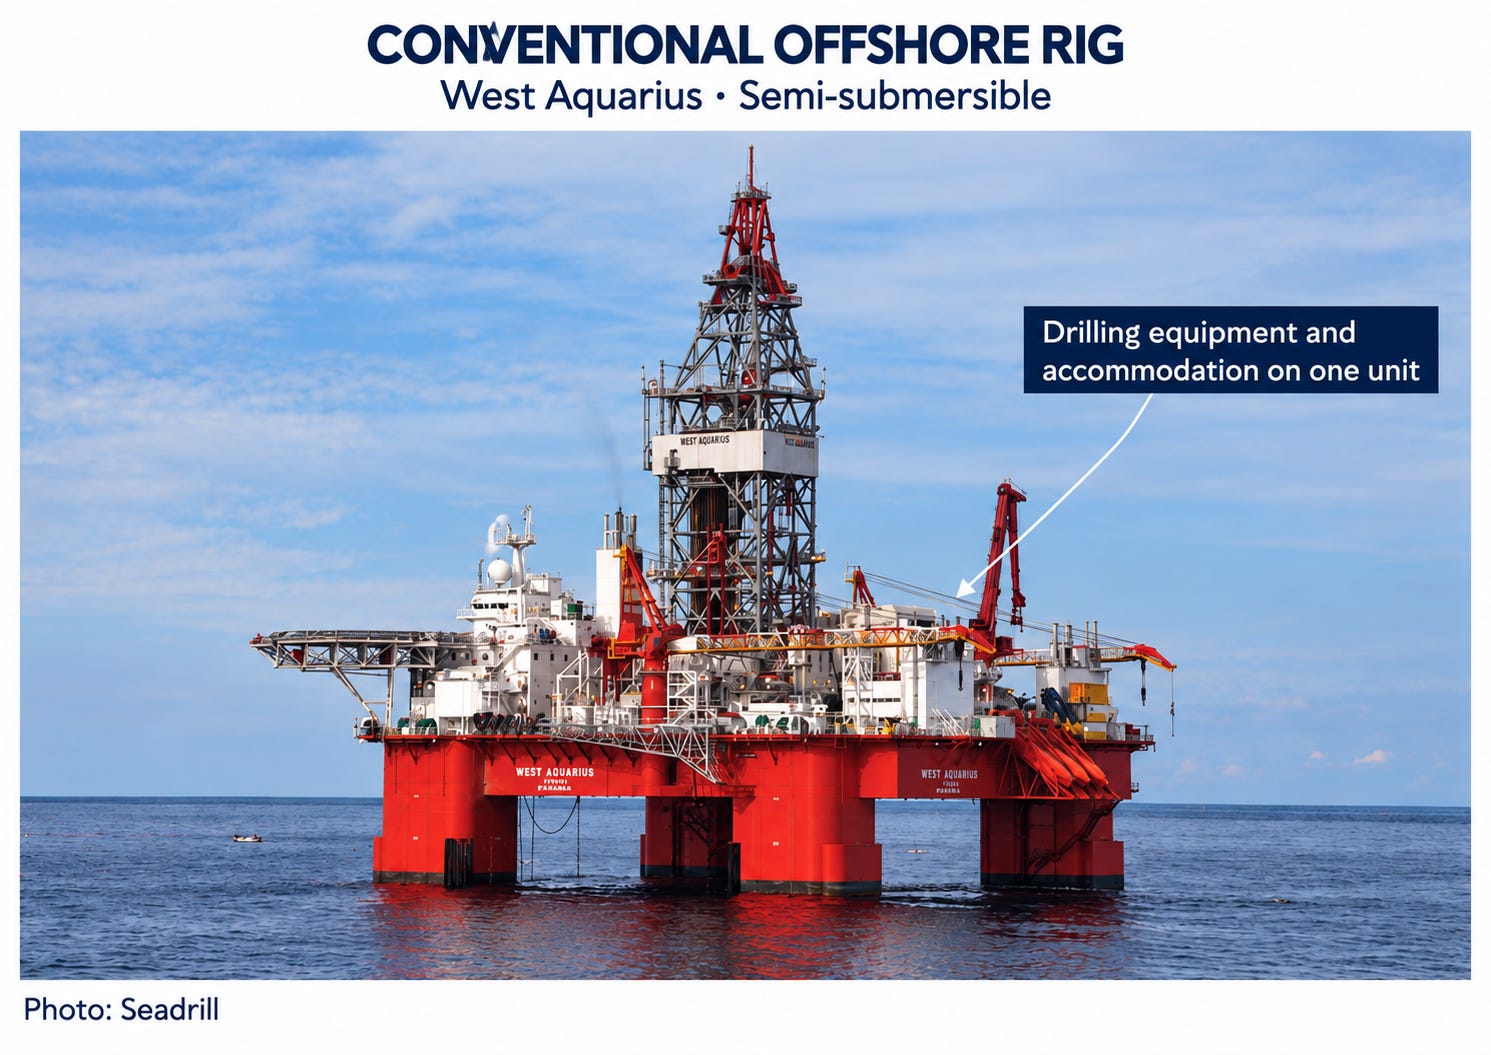
This only works where you have a lot of small platforms in calm, shallow water, which mostly means the Gulf of Thailand. That is why the whole world has only sixteen of them.
Then I went looking for proof of the number I liked most, and I found it. It is a Seadrill press release from June 21, 2023. Seadrill was selling three tender rigs, and the price for all three together was about $85 million. The buyer is the company that is now part of SED.
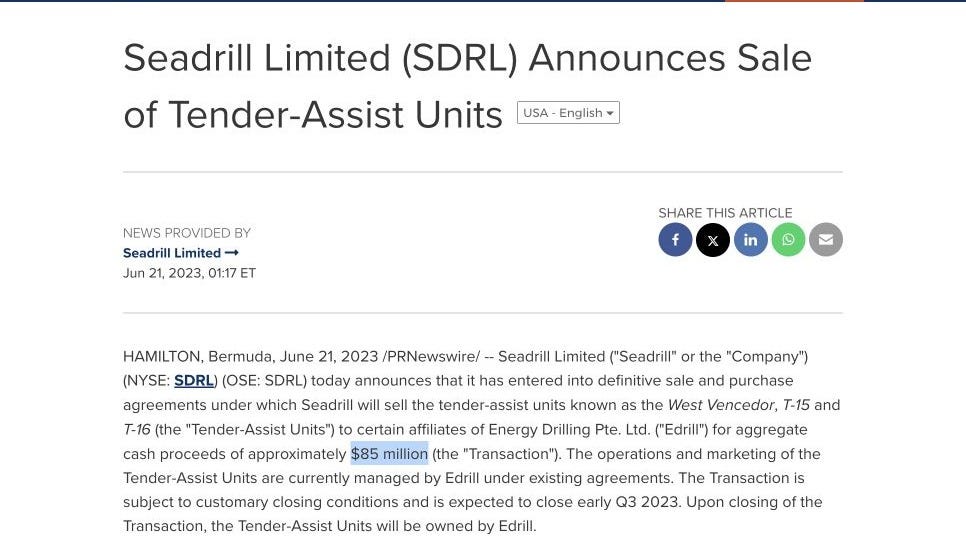
So it was true. And I already own offshore drillers, so I wanted all of it to be true.
There are several very good write-ups about this company here on Substack. They call it one of the cheapest dividend stories in offshore. But if this is so obvious, who is selling it to me at this price?
So I opened every stock exchange filing since the merger and put them in order by date. Most of them are boring. But when you read them in order, eight dates stand out, and together they tell a story that the numbers don’t.
Below I go through all eight. One of them is a sentence the company wrote 27 days before its stock fell 13% in a single day. And at the end you get what I answered my reader.
