

I want one thing.
A company that buys 80 percent of itself while the market looks the other way. Dillard’s did it. 73.9 million shares in 2010, 15.6 million today, revenue flat for twelve years, stock 27 to 624. I wrote that post two weeks ago. It was history.

This one is a hunt.
Three candidates. Crocs. CNX. Group 1. All three eat their own shares. All three are cheap. All three are hated for a reason the market thinks is permanent.
Group 1 has the receipts. In July I asked you which company to add to the list. Seventy of you voted.
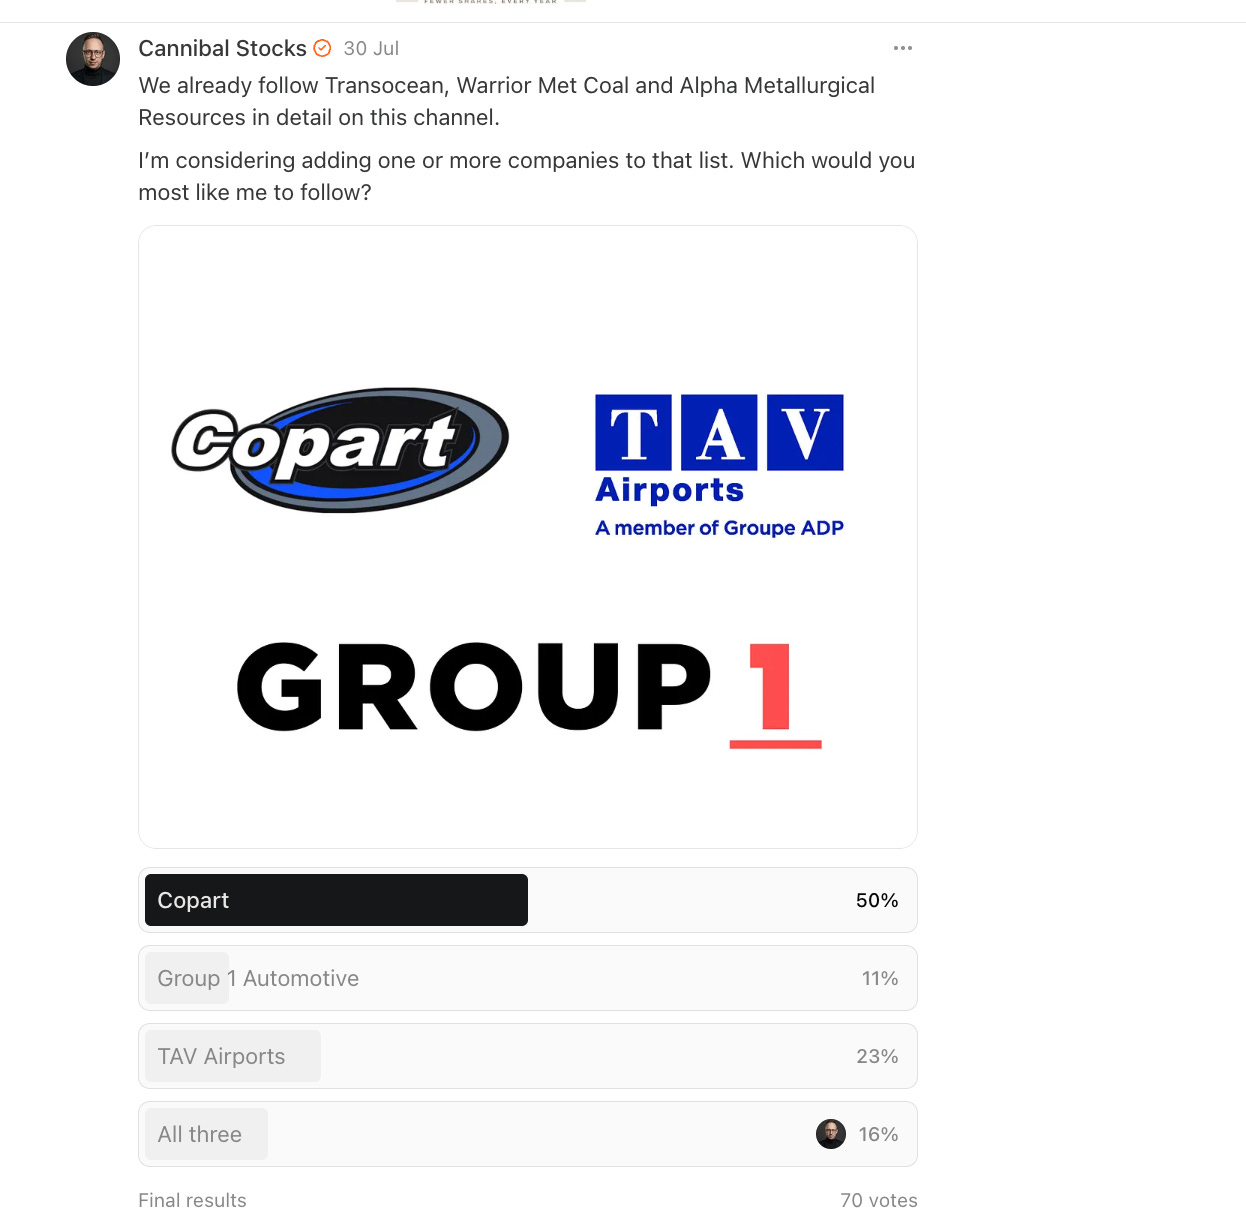
Copart took half. An airport in Turkey took a quarter. Group 1 got eight votes. A dealer of new cars lost to a dealer of crashed ones, more than four to one. Kicked out of the Russell growth indexes in June and now voted down by the most contrarian readership on Substack. For a cannibal, hatred is the price of admission.
Group 1 walked in for free. 🙂
I built two screens. One ranked by float, one by cash yield. Two different winners. I threw both out and read the transcripts myself. Eight earnings calls. Every proxy. Every 8-K. What the men said with their mouths and what they did with the checkbook.
The rule
Everything below runs on one sentence.
At a constant multiple, the share of free cash flow that goes to buybacks, divided by price to free cash flow, is the percent of the company that disappears every year.
Ten times cash, all of it into buybacks, and ten percent of the company is gone in a year.
Growth does not change it. Revenue does not change it. Only two things do. The price the market charges, and whether the man in the corner office picks up the phone to buy something else.
Dillard’s passed four tests for sixteen years. Cash. Hatred. Speed. And the phone stayed on the hook. Zero acquisitions from 2010 to 2026. Not small ones. Zero.
How far they have come
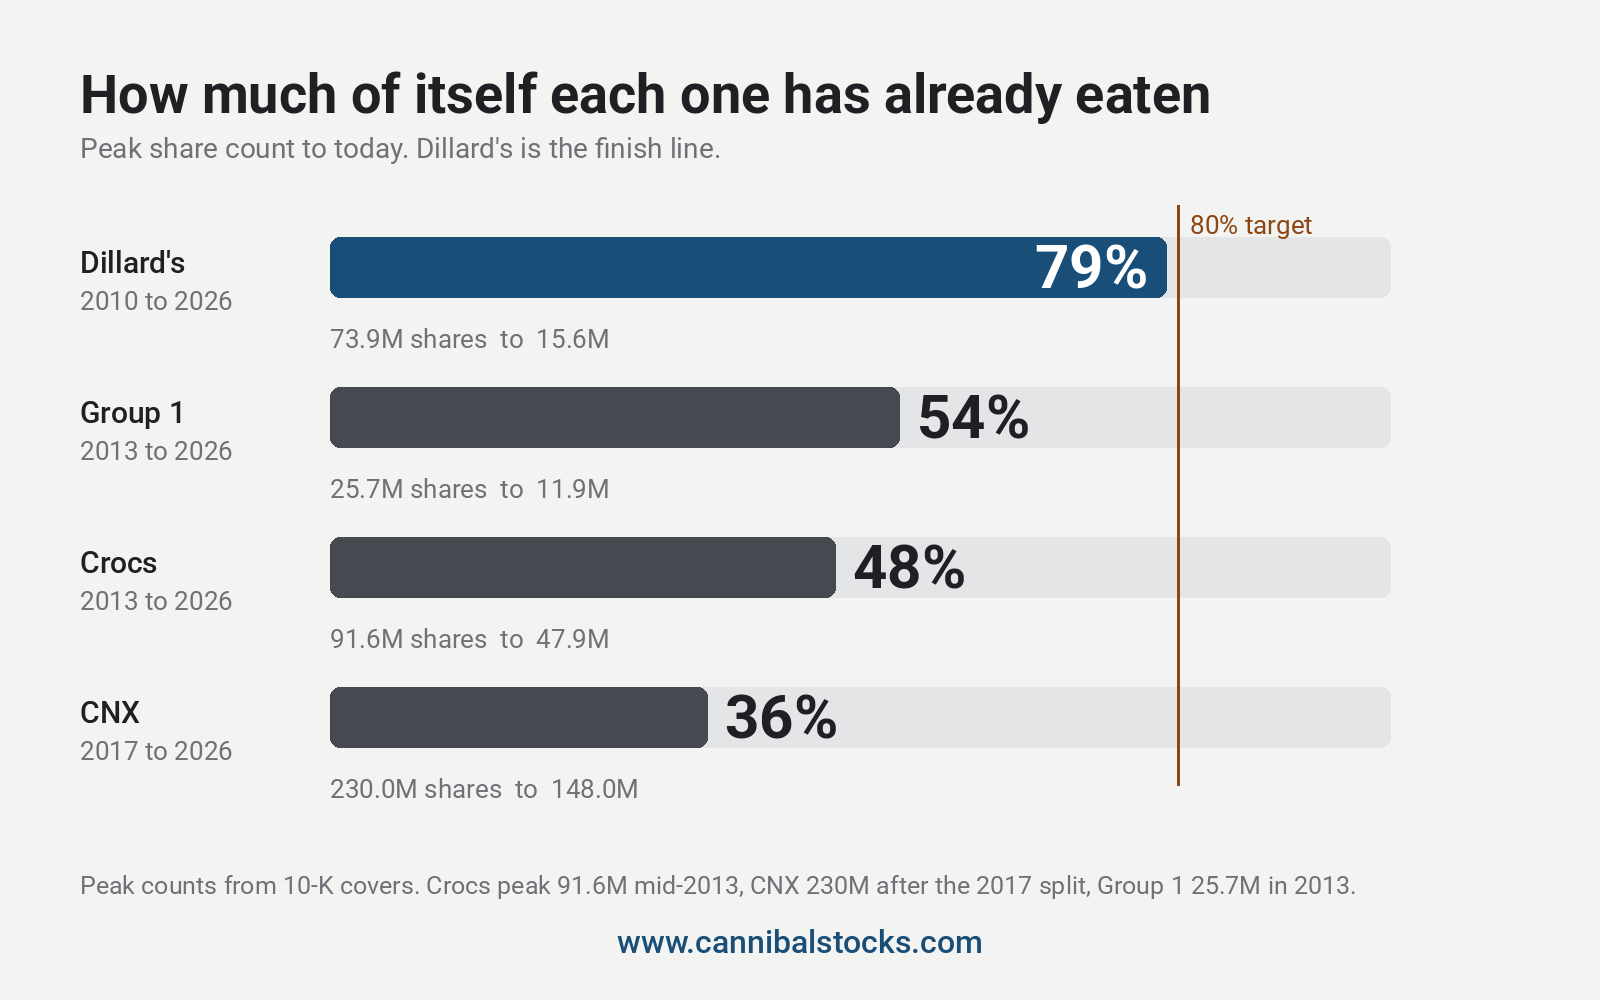
Group 1 leads. Crocs next.
CNX last, and its number lies. Last October CNX was at 134.8 million, a forty percent cut, before the convertible notes it sold in 2020 came due and put 12.6 million shares back on the table. It is the only one of the three that has ever gone backwards.
Dillard’s is the line at 79. Two of them are already past the halfway mark. One is not, and its road is longer.
Three companies, three different answers. The math picks one. The man in the corner office picks another. The third looks the most like Dillard’s on paper and the least like it in real life.
When I was done, two of the three went into my portfolio. I am not telling you which two. Not in this post.
Same four tests. Ten points each. Four rounds.
One note before the line. On October 1 the annual price goes from $159 to $199. Join before then and you keep $159 for as long as you stay.
