
Part 2 of the Li Lu series. Part 1, How Li Lu Invests, is free.

Go on Amazon right now and search for foam shoes with holes in them.
Ten dollars. Same mold, same holes, same strap. Nobody will know the difference from six feet away.
Crocs sells the same shoe for fifty, and the Crocs brand keeps 63 cents of every dollar as gross profit. On and Hoka need a 160 dollar sneaker to get close. Crocs does it on a piece of foam a Chinese factory will copy for you by Thursday.
The easiest product on earth to copy, and in 24 years nobody has copied the business.
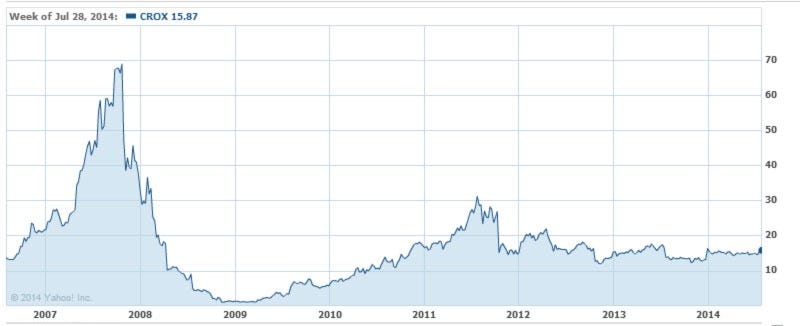
Because in 2002 a foam shoe was not a brand. It was a boat shoe. It was the thing you bought at a gas station. Three guys at a Fort Lauderdale boat show sold 24,000 dollars of them that year. Five years later, 847 million. A year after that the company nearly died, because it grew like a fad and was run like one. Too many styles. Mountains of shoes nobody wanted. A 185 million dollar loss. Stock from 75 dollars to 94 cents.
Then it came back, and this time the shoe had a name.
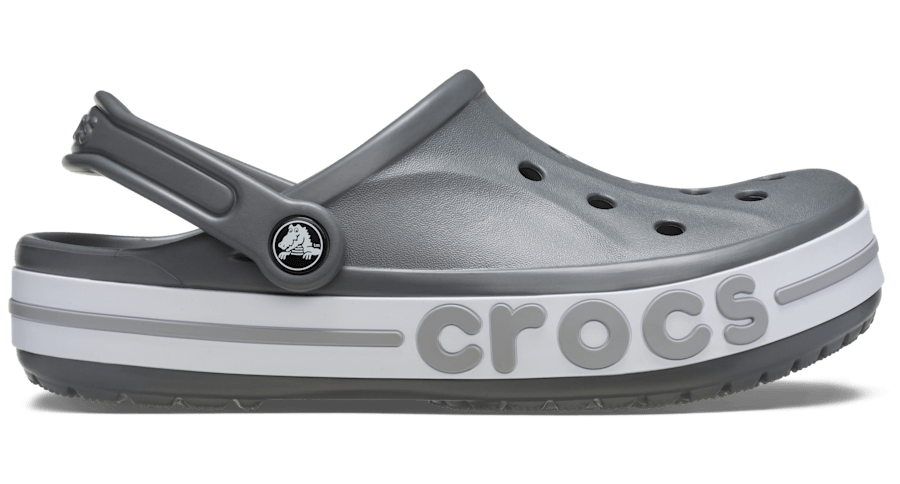
Half the world thinks it is the ugliest thing ever made. The other half owns four pairs. That argument is the moat. Nobody argues about Skechers.
And it is rare. Crocs itself spent 2.5 billion dollars trying to build a second brand in casual footwear. It failed and wrote off 737 million. The company that owns the only brand in foam could not buy another one. Brands like this do not get built twice. Not by competitors, not even by Crocs.
Li Lu looked at all of this and bought.
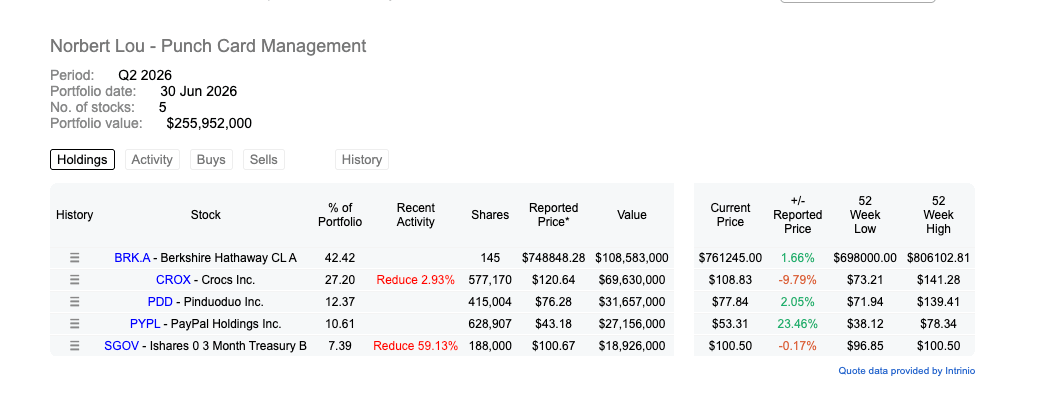
So did Norbert Lou of Punch Card, who runs one of the most concentrated funds alive and does not buy things that need to grow. Crocs is his second largest position. Only Berkshire is bigger. He trimmed it three percent last quarter, which I mention so nobody has to email me about it. 🙂
His page
Fourth quarter 2025, Himalaya Capital opens the position. 628,159 shares. The stock touched 73 dollars that November. First quarter 2026, he adds 41 percent. Second quarter, six names leave his filing. Bank of America, H&R Block, Occidental, S&P Global, Moody’s, MSCI. PDD more than doubles. This one stays, every share. 887,093 on June 30.
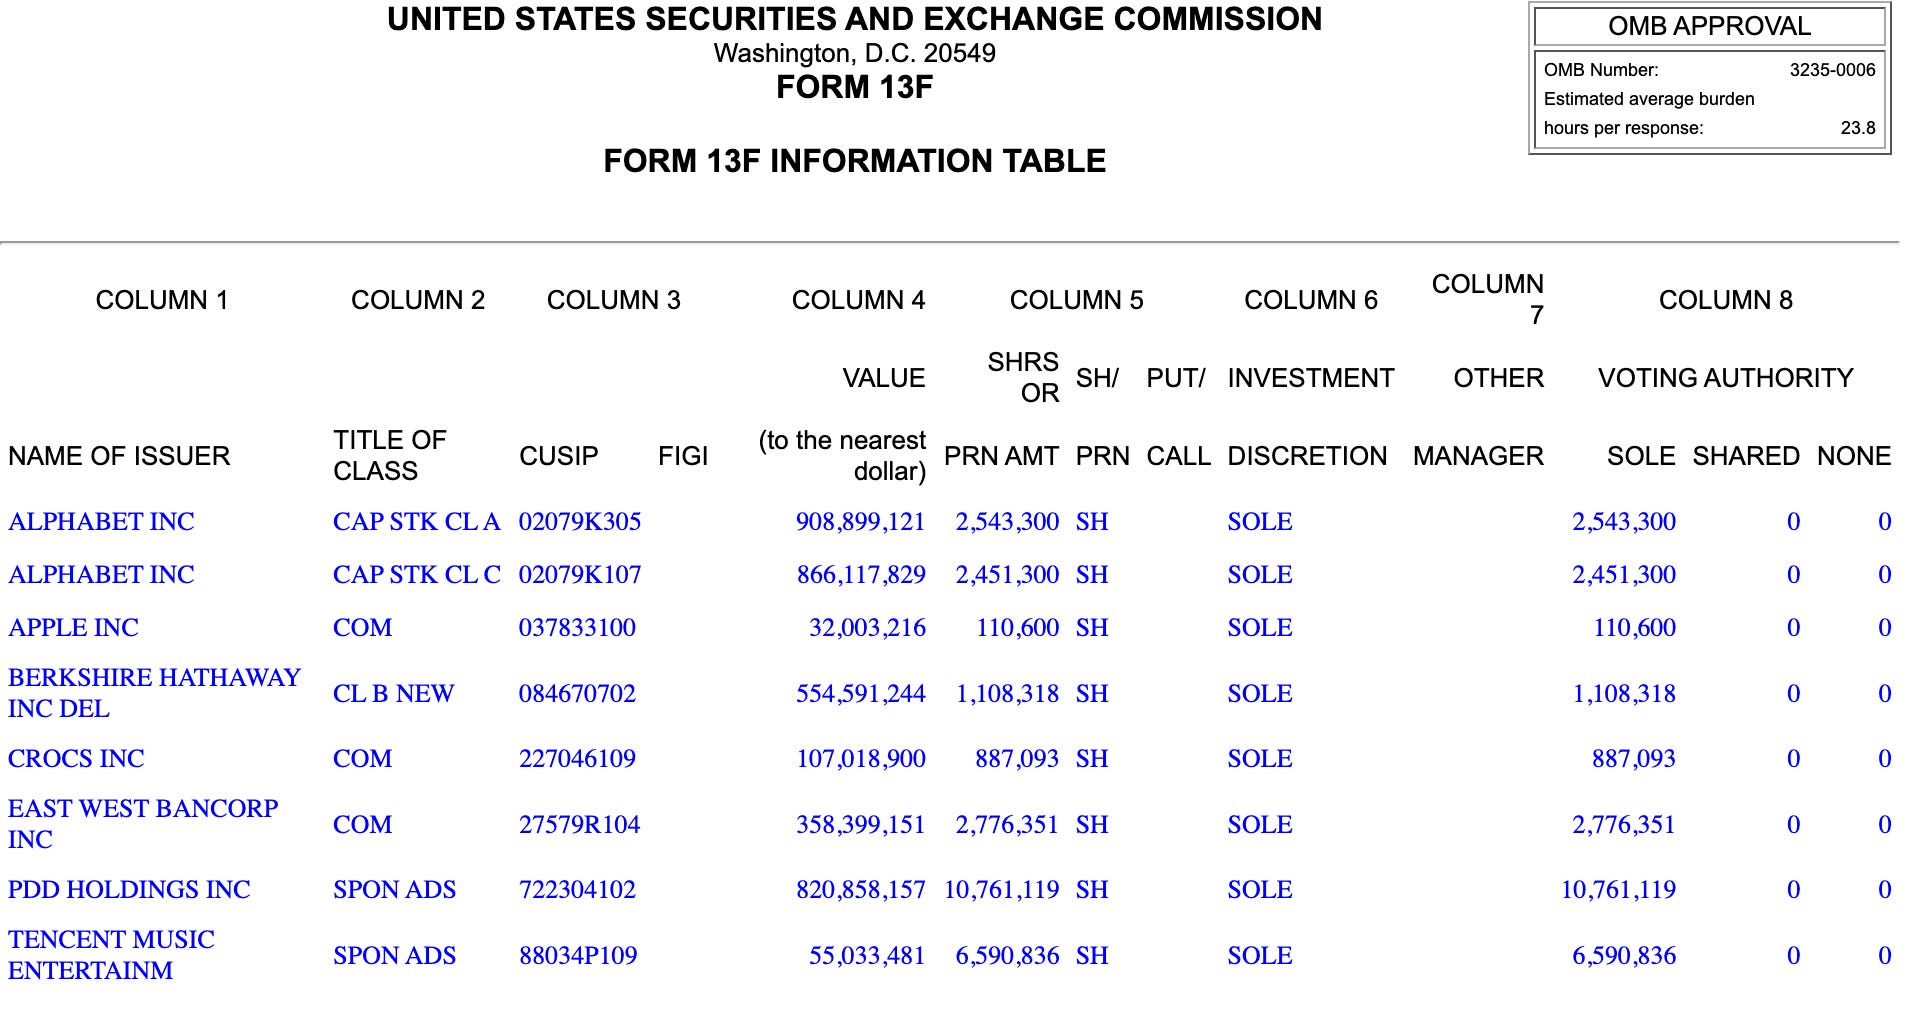
One honest line first. It is 3 percent of his American book. Alphabet, PDD and Berkshire are 85 percent. Timberland was a bet. This is a page he is still writing.
What did he pay? The filings show what he holds, not what he paid. The stock spent most of that winter in the eighties. Call it 85.
At 85 the whole company cost about 4.3 billion dollars. In 2025 it produced 660 million of free cash. Six and a half times cash. A 15 percent cash yield. For the only brand in foam.
Why cash and not profit? Because the profit line for 2025 says Crocs lost 81 million dollars. It did not. That is the HEYDUDE write-off, 737 million of accounting for money that actually left the building in 2022. So I ignore profit and follow the cash. Cash left after paying suppliers, staff, interest and taxes, minus what goes into stores, factories and software. In 2025 that was 710 million in, 51 million out. 660 million left over. Cash does not care about goodwill.
Cash can lie too. It gets flattered when a company sells down inventory or skips investment. Stock comp, 37 million a year, quietly leaks out the side. And 660 is the worst year of the last three. In 2024 it was over 900. Tariffs and HEYDUDE ate the difference. I use 660 anyway. Everything below runs on the worst year.
Why the room walked past
Three reasons. All true.
The chart. Declared a fad in 2008 when it nearly died, in 2022 when it bought HEYDUDE at the top and fell 75 percent, in 2025 when it wrote HEYDUDE down.
The deal. HEYDUDE, a canvas loafer brand, bought in February 2022 for 2.5 billion dollars. Its sales are down a quarter since 2023. Write-off of 737 million. Shareholders are suing over stuffed wholesalers. Allegations, for now. And the FTC made HEYDUDE pay two million for burying its bad reviews. A good brand does not need to hide its reviews.
The tariffs. Forty five percent of Crocs brand production comes out of Vietnam. Tariffs took 300 basis points off the gross margin last winter and 160 in the second quarter.
And a fourth reason, six weeks old. On July 30 Crocs reported a record quarter and raised its outlook for the year. The stock fell anyway. The margin is bleeding tariffs and the next quarter is guided flat. It is down about 15 percent since.
I use 110 dollars in this post, roughly where it trades as I write. Forty eight million shares. 5.3 billion dollars for the whole company. Eight times last year’s free cash. A 12.5 percent cash yield. Almost 14 dollars of cash per share.
Fad, bad deal, lawsuits, tariffs, and a chart that just broke. Pass. That is the note a normal fund manager writes.
Li Lu wrote down homework.
While I was writing this
On September 14 a Form 4 landed on EDGAR. Thomas Smach, chairman of the Crocs board since 2011 and a director since 2005, bought 4,000 shares on September 10. Average price 109 dollars. Almost half a million dollars of his own money, at the same price I use in this post.
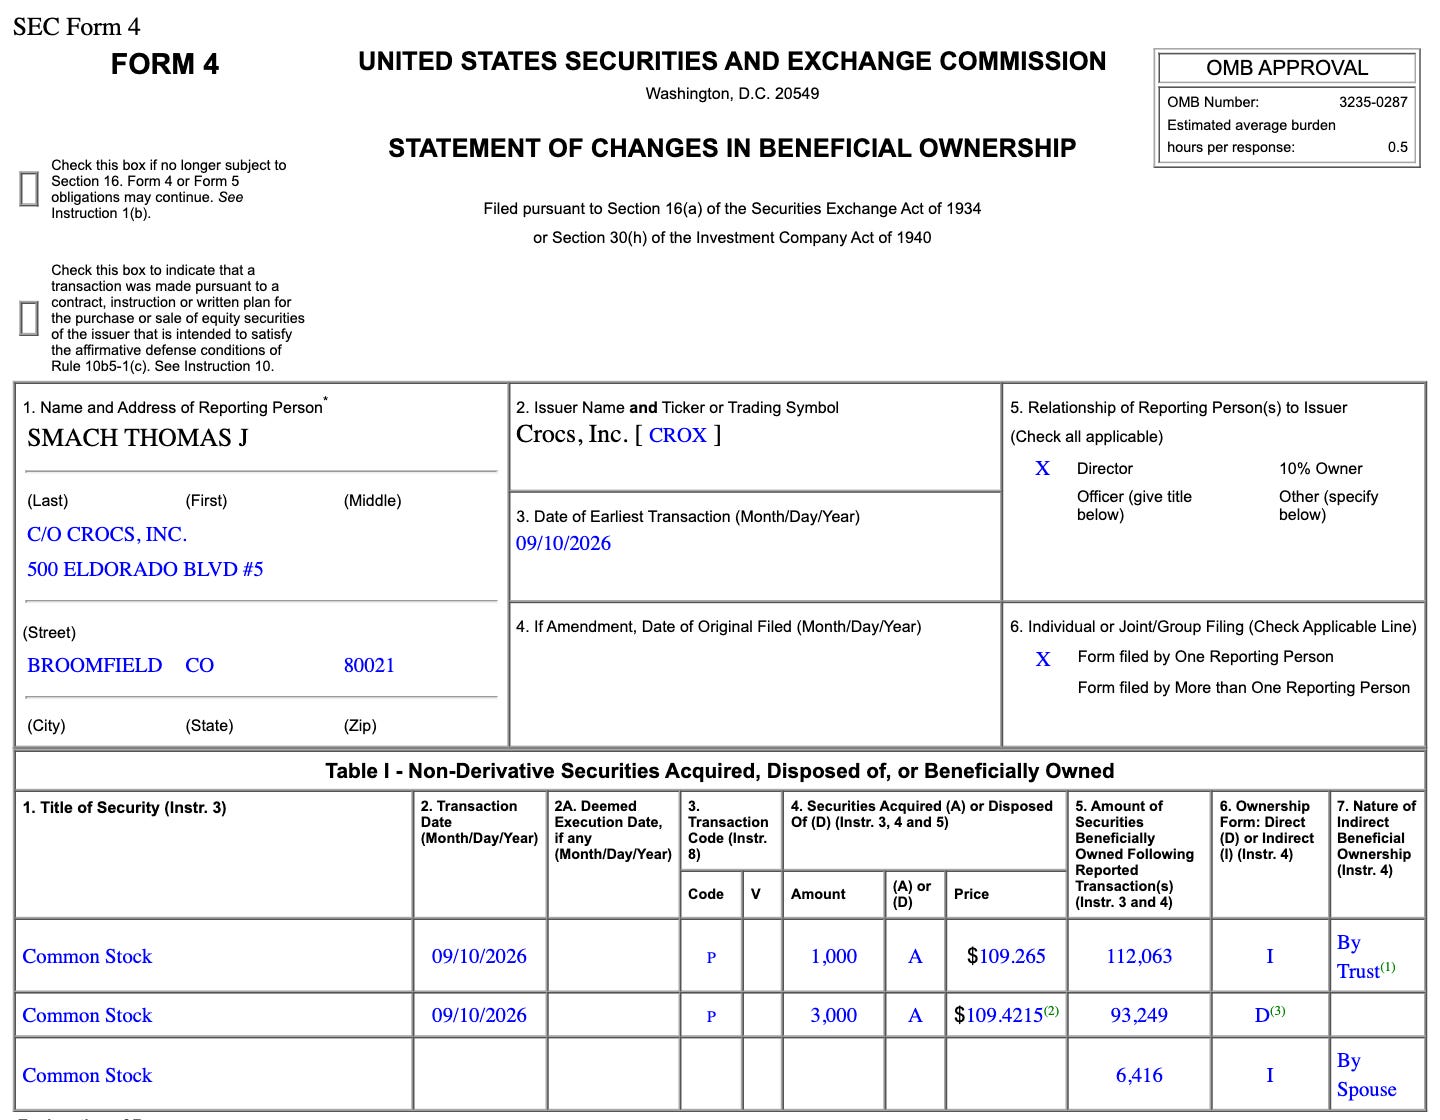
Receipts, honestly. He sold 10,000 shares in February at 98 and 100. Now he buys 4,000 back at 109. It is his first purchase since 2023, when he was buying at the same prices. He still owns about 210,000 shares, so this is two percent added, not the house.
I would not build a thesis on 4,000 shares. But this is the man who sat in that boardroom through 2008, through HEYDUDE, through the write-off. He read the same flat guidance you did. And he wrote a check. A data point, not a thesis. Li Lu would have written it down.
The stores
Li Lu walked into shoe stores in 1998 and heard that kids wanted Timberlands and nobody had stock.
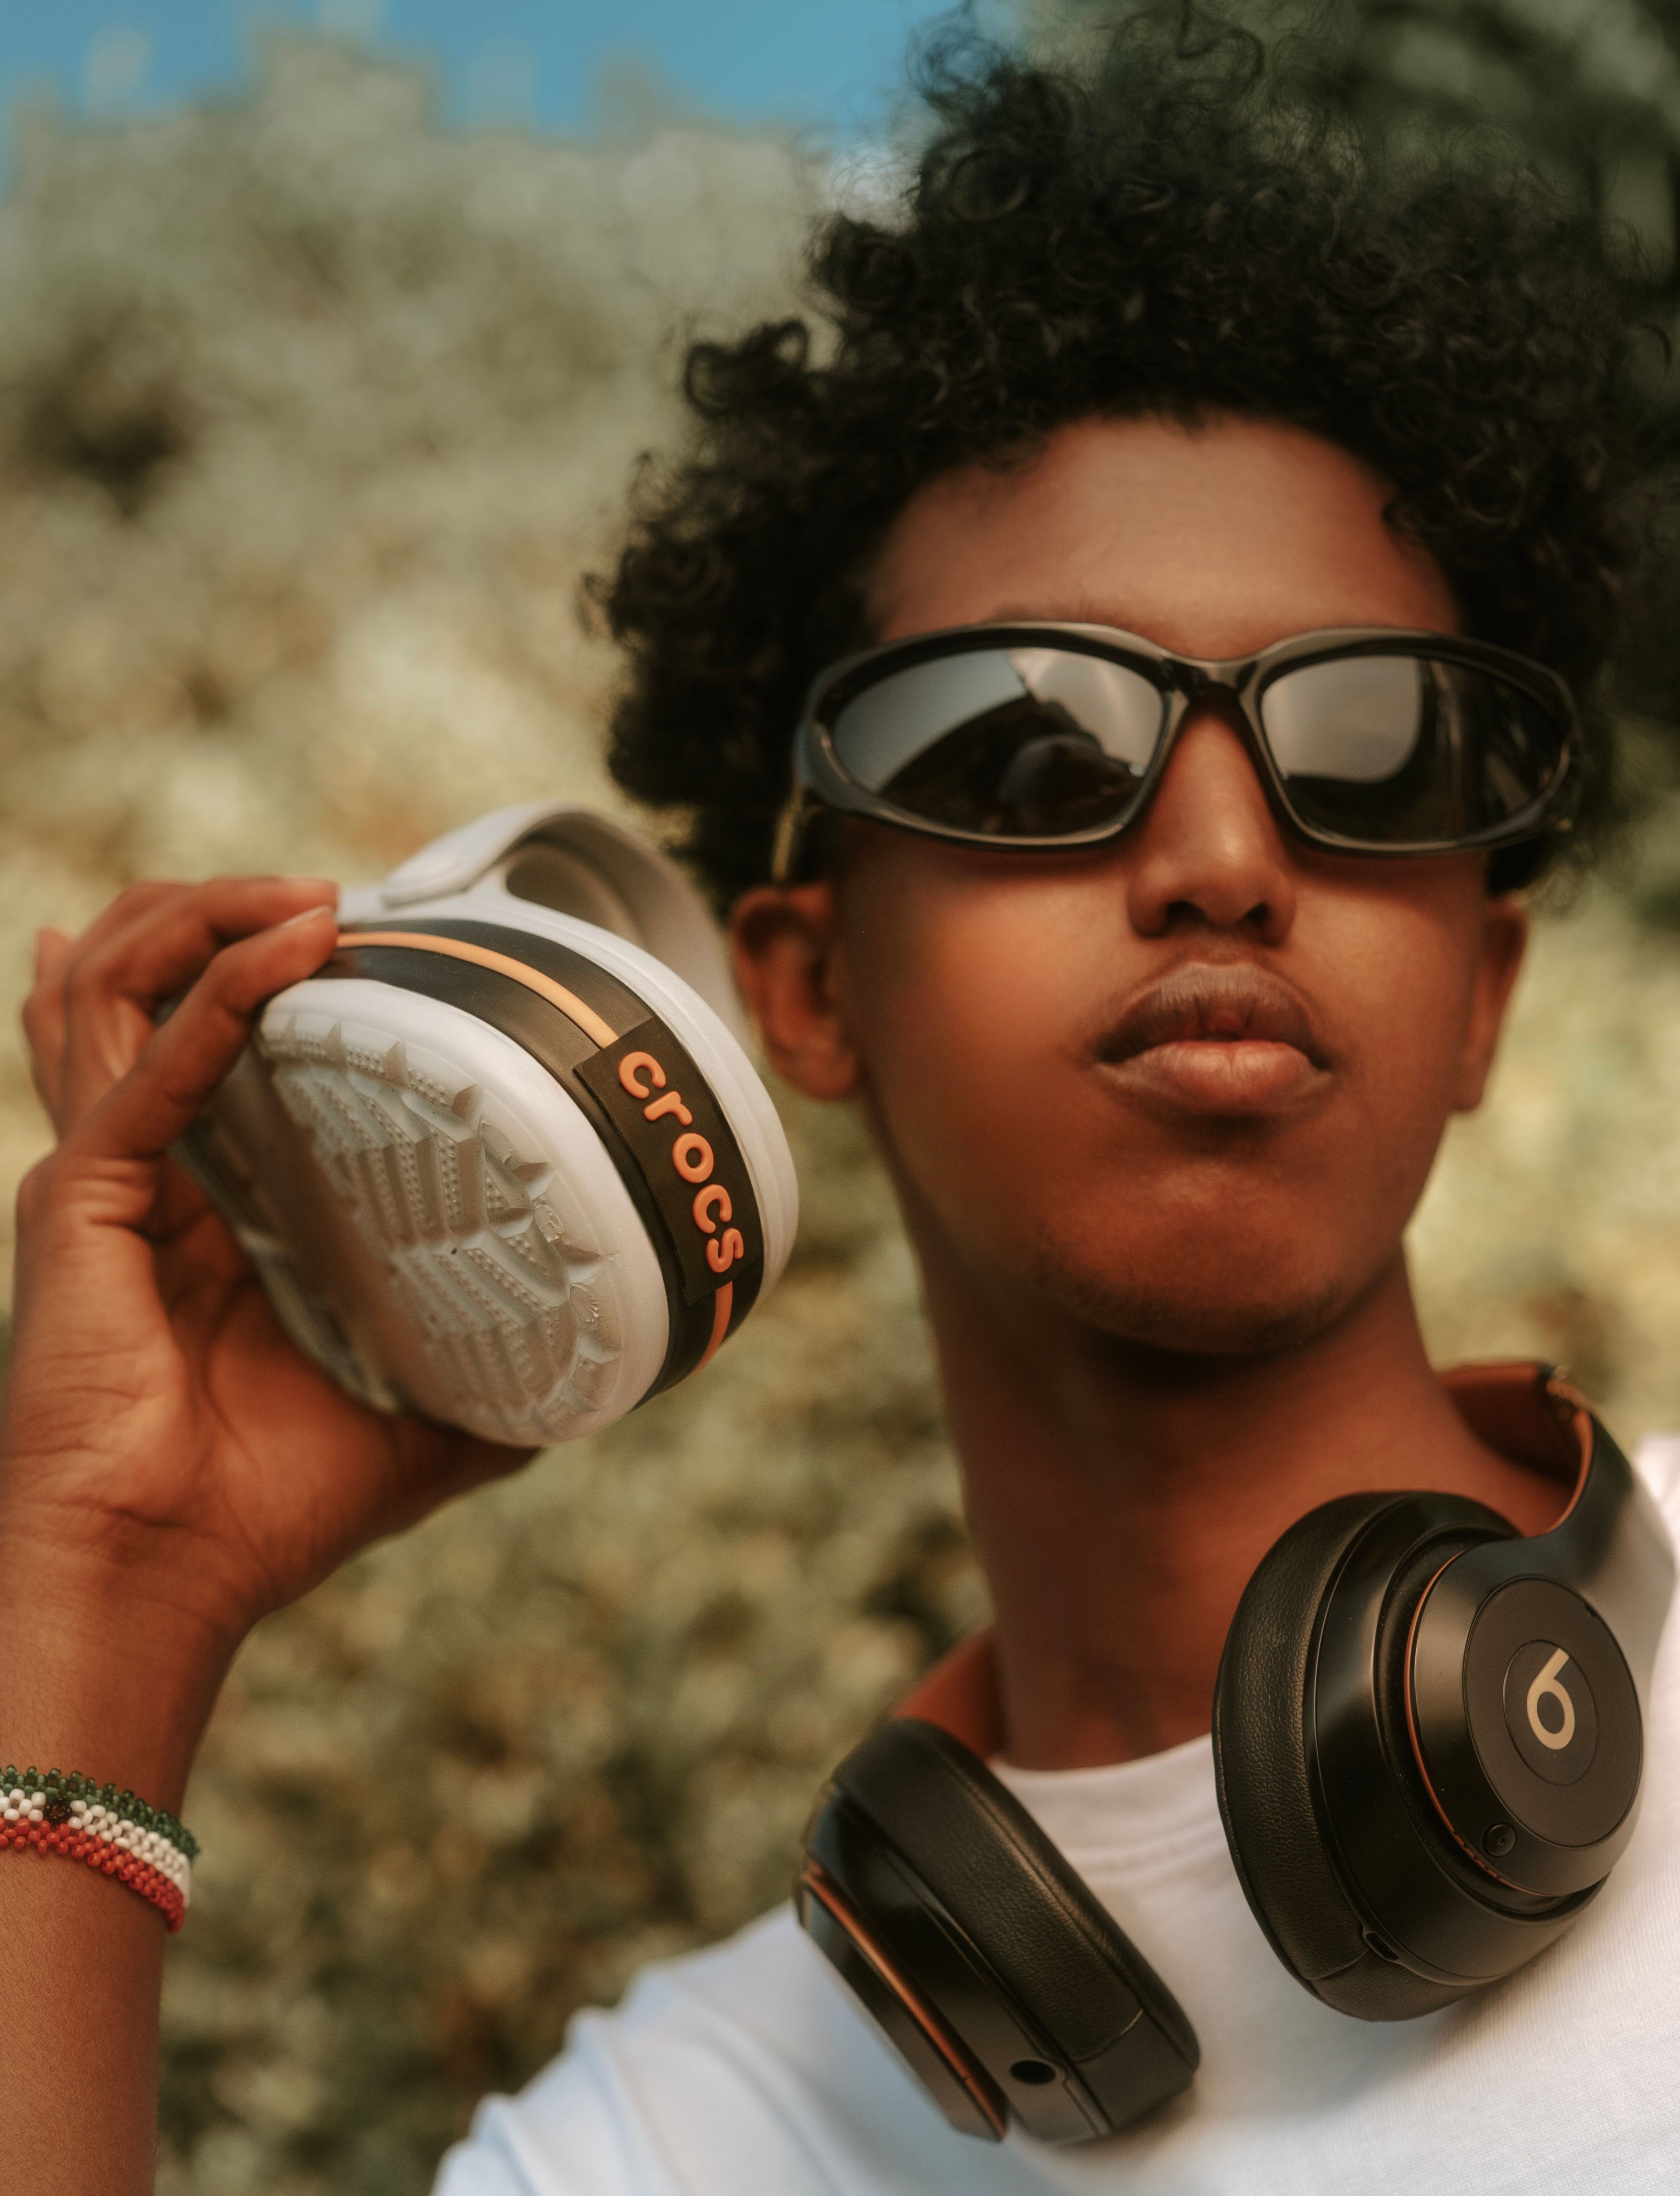
Walk in today.
The Crocs brand just did a billion dollars in one quarter for the first time ever. Direct to consumer up 13 percent. International up 8. China, India and Japan growing double digits while North America sits flat.
HEYDUDE is 18 percent of revenue and shrinking. The clog is doing the work. Below the line, how fast this company can eat itself, and what that means for every share that is left.
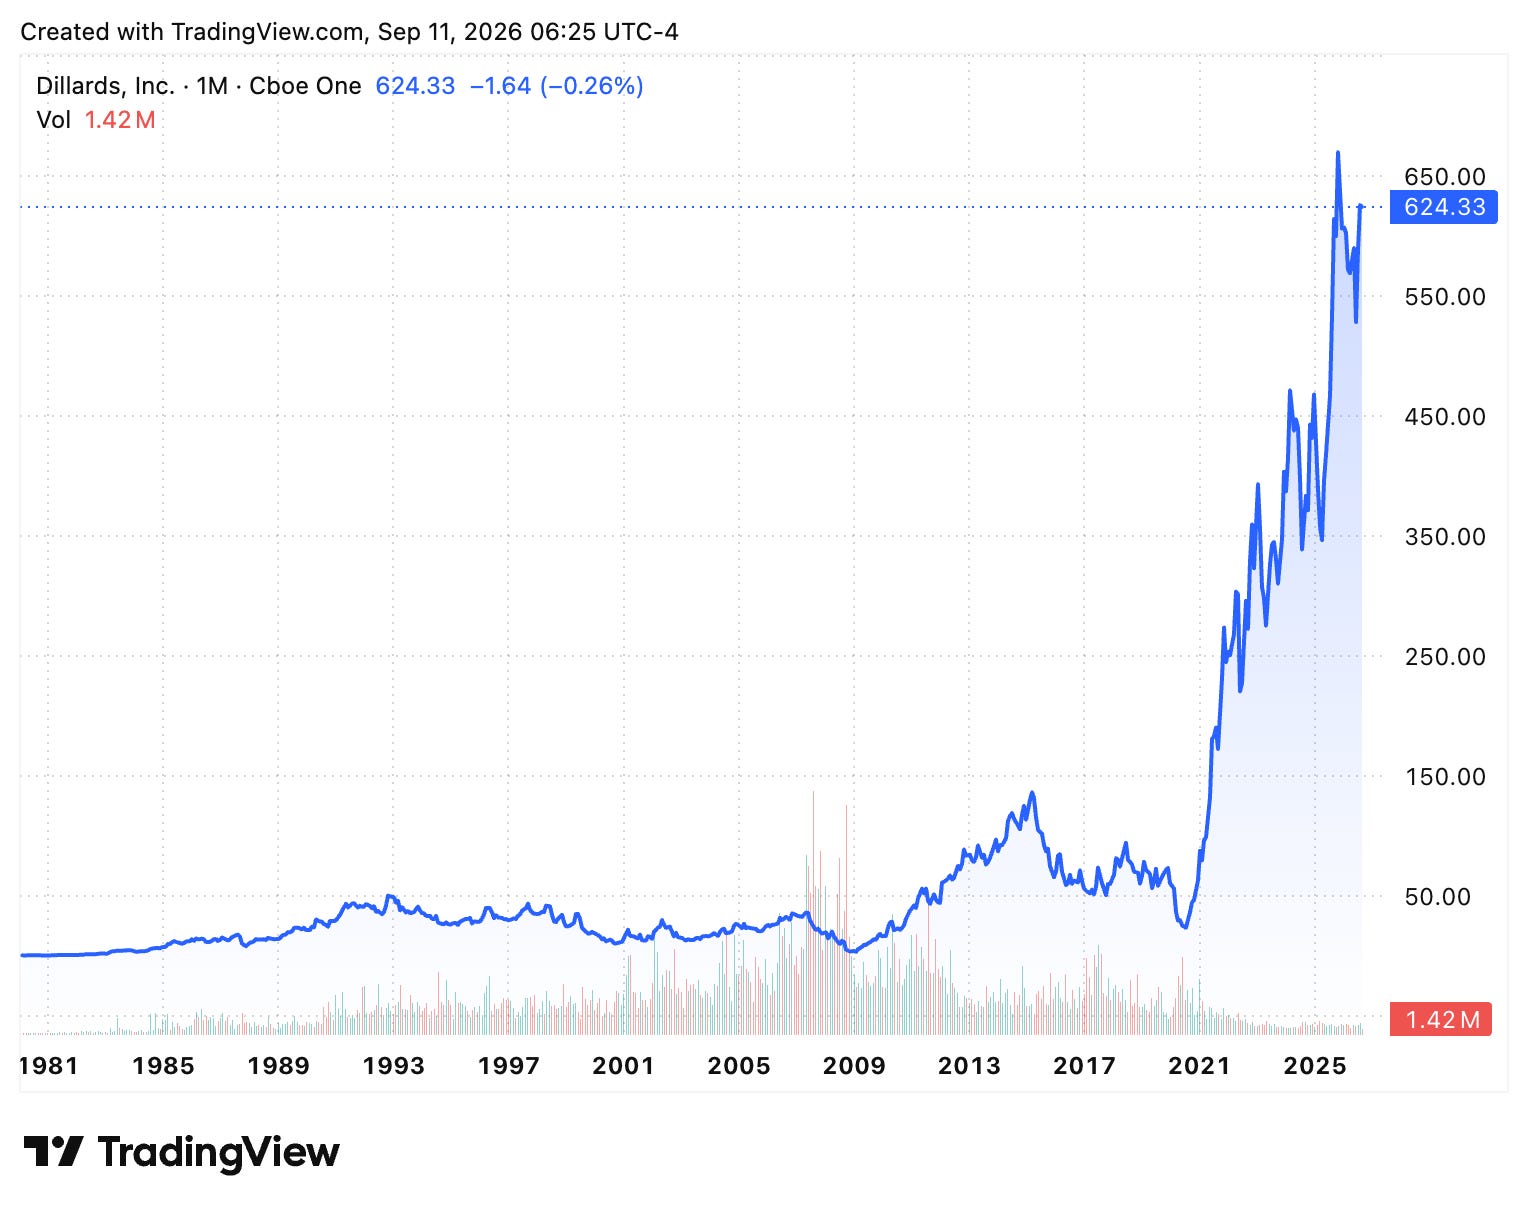
Then the real question. That chart is Dillard’s. Same revenue for twelve years, a stock that went from under 30 to 624, and a 30 dollar dividend this January.
Whether Crocs can do that is what I am really trying to find out…